

Yes. Non-residents can get a mortgage in Spain in 2026, but on stricter terms than residents. Banks usually lend 60–70% of the purchase price or valuation (whichever is lower), over 20–25 years, and the loan must normally be repaid by age 75. Plan on bringing around 40% of the price in cash to cover the deposit, taxes and fees.
Last updated: 13 October 2026
How much will a Spanish bank lend to a non-resident?
Most banks finance up to 60–70% of the lower of the purchase price and the bank’s own valuation, compared with up to 80% for residents (HelpMyCash, 2026; Costa Luz Lawyers, 2026). For Spanish tax purposes you are a non-resident if you spend less than 183 days a year in Spain.
| Residents | Non-residents | |
|---|---|---|
| Maximum financing | Up to 80% | Usually 60–70% |
| Typical maximum term | Up to 30 years | Usually 20–25 years |
| Age at the end of the loan | Usually 75 max. | Usually 75 max. |
| Total debt vs net income | About 30–35% | About 30–35% |
| Cash needed (deposit + costs) | About 30% | About 40% |
These are market references, not offers: each bank sets its own limits depending on your income, the currency you earn in and the property.
What interest rate do non-residents pay in 2026?
Non-resident mortgages are priced above resident ones: average rates were above 3% in 2026, against around 2.5% for residents (HelpMyCash). Variable mortgages in Spain follow the 12-month Euribor, which was 3.191% on 9 October 2026, up from 2.209% a year earlier (euribor-rates.info). Many international buyers prefer a fixed or mixed rate for certainty.
What documents do I need?
- Passport and NIE (Spanish foreigner identification number).
- Proof of income: last payslips and employment contract, or accounts and tax returns if self-employed.
- Your latest tax return and a tax residence certificate from your home country.
- Bank statements for the last six months and a summary of existing debts.
- A credit report from your country of residence, where available.
- Sworn translations of documents that are not in Spanish.
You will also need a Spanish bank account. Banks generally prefer buyers who earn in strong currencies, such as euros, pounds, US dollars or Swiss francs.
How much cash do I need on top of the mortgage?
Around 40% of the price for a non-resident: the 30–40% the bank does not finance plus purchase taxes and fees. On a new-build home in Andalucía the main taxes are 10% VAT (IVA) and 1.2% stamp duty (AJD), plus notary, land registry and legal fees. See our full breakdown of costs and taxes when buying a villa in Marbella (in Spanish).
Who pays the mortgage costs?
Under Spain’s mortgage law (Ley 5/2019), the bank pays the notary, land registry and management fees for the mortgage deed, and since a 2018 tax reform it also pays the stamp duty (AJD) on that deed. The borrower pays the property valuation and any opening fee, which is typically around 0.5% if the bank charges one.
How long does it take to get a mortgage in Spain?
Usually 8–12 weeks from application to signing. Before signing, the bank must give you the European Standardised Information Sheet (FEIN) and a warnings sheet (FiAE), and you have at least 10 days to review them. The notary then checks with you, free of charge, that you understand the terms.
- Get your NIE and open a Spanish bank account.
- Ask two or three banks or a mortgage broker for an approval in principle.
- Sign the reservation on the home and order the bank’s valuation.
- Receive the binding offer (FEIN) and wait the 10-day reflection period.
- Sign the purchase deed and the mortgage deed at the notary on the same day.
Can I get a mortgage for a new-build villa?
Yes. With a new-build or off-plan home, the mortgage is normally arranged for completion, when the purchase deed is signed and the bank can value the finished home. Our guide to buying a new-build villa in Benahavís explains each step of the process.
What should non-residents watch out for?
- Currency risk: if you earn in pounds or dollars and pay in euros, exchange rates change your real monthly cost.
- Total cost, not just the rate: compare the APR (TAE), linked products and early repayment fees.
- Valuation gap: the bank lends on its valuation; if it comes in below the price, you cover the difference.
- Independent advice: use an independent Spanish lawyer for the purchase and the mortgage.
Buying at Tierra Viva with a mortgage
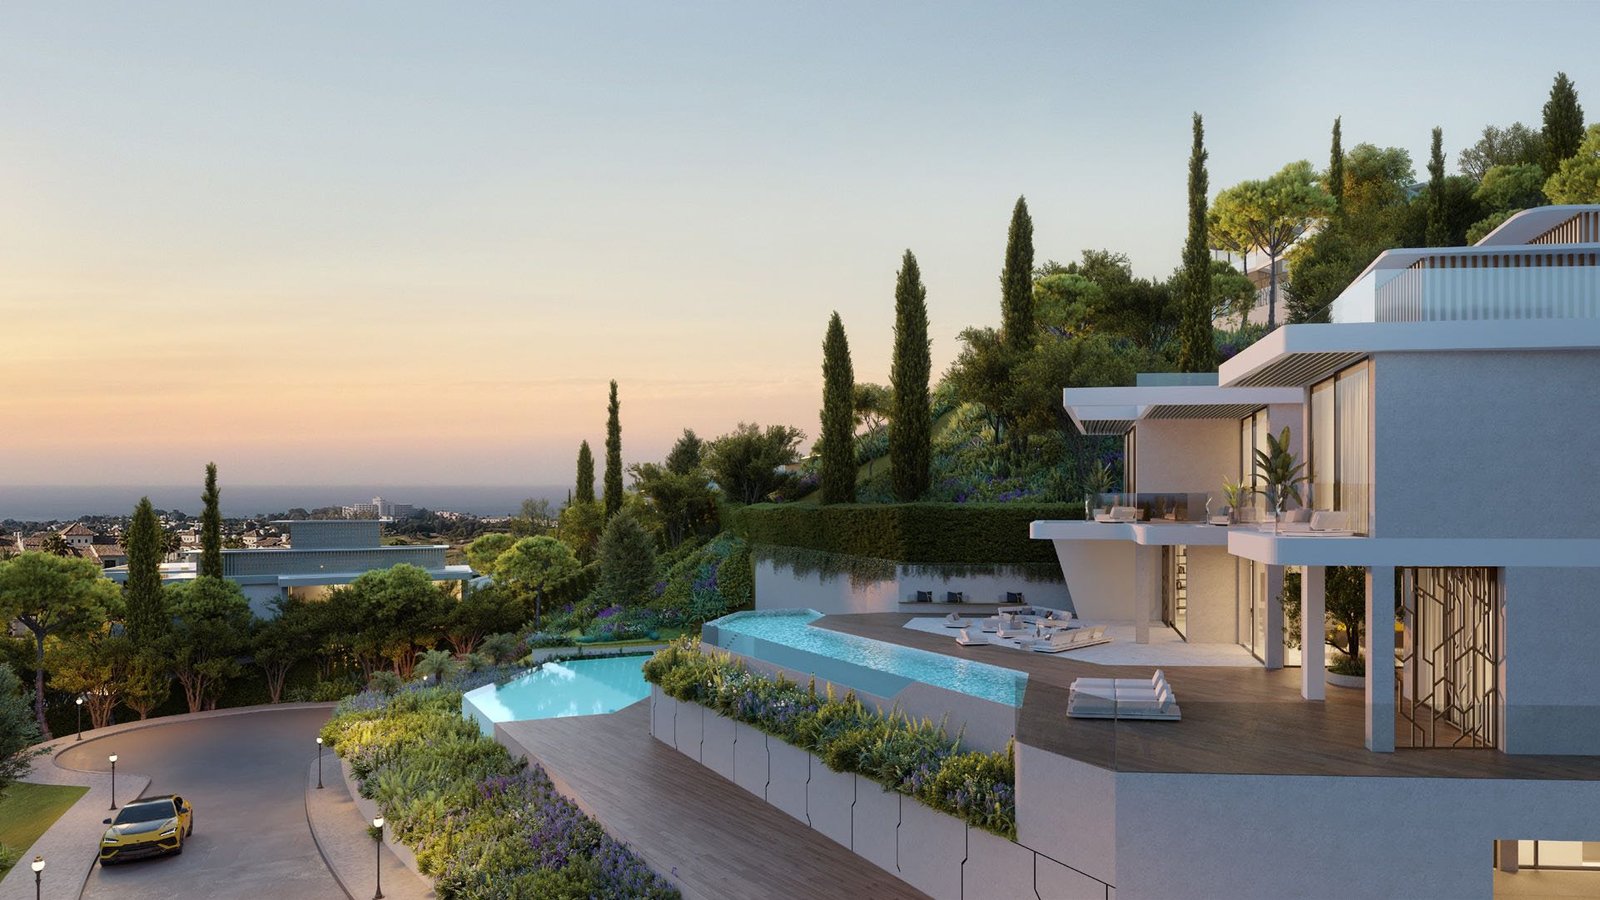
Tierra Viva is a gated community of 53 mansions in Benahavís designed with Automobili Lamborghini and developed by Dar Global. Many buyers pay in cash, but financing is possible. In a private presentation we explain the purchase process for your case and share the brochure and availability. You can also read our page on investing in luxury villas in Marbella.
FAQ
Can a foreigner get a 100% mortgage in Spain?
Not as a non-resident. Spanish banks keep a deposit requirement, usually 30–40% of the price for non-residents, plus taxes and fees.
Do I need to be resident in Spain to get a mortgage?
No. Spanish banks lend to non-residents with a NIE, a Spanish bank account and proof of stable income. The terms are simply stricter than for residents.
Is it better to use a Spanish bank or a broker?
A broker can compare several banks and is useful if your income is complex or in another currency. Either way, ask for the FEIN of each offer and compare the APR.
This article is general information, not financial advice. Conditions vary by bank and buyer profile; confirm them with your lender and an independent adviser.
Book a private presentation
We meet every buyer privately: a presentation at our office or by video call, with the official brochure, floor plans and availability. Message us on WhatsApp or call +34 617 455 454.


Comments are closed